Fear of a workplace wipeout across the banking sector grew on Friday as lenders turn to AI to automate routine work, cut costs and lift productivity, with Barclays preparing to shed 5,000 staff and Australia’s biggest banks already announcing thousands of redundancies.
The job cuts equivalent to about 5 per cent of the British bank’s global workforce, follow National Australia Bank’s announcement that it would axe 4,000 roles by June 2027.
ANZ Bank has also dumped 4,500 staff, with CBA expected to lose around 1,000 roles this year.
Sign up to The Nightly’s newsletters.
Get the first look at the digital newspaper, curated daily stories and breaking headlines delivered to your inbox.
By continuing you agree to our Terms and Privacy Policy.
In September, Australia’s unemployment rate rose to a five-year high of 4.7 per cent, although the Reserve Bank is not currently forecasting large job losses linked to AI’s ability to replace workers.
The Finance Sector Union (FSU) has labelled NAB’s job cuts “disgraceful” and challenged it to prove they’re not just about boosting profits.
Other economists believe AI will eventually create more jobs than it displaces and lower inflation to improve overall living standards.
“It’s possible unemployment jumps and it’s more likely if governments make it more expensive to employ people,” said former HSBC Economist Julian Jessop.
“But there’ll be winners from AI. When companies or people have more money from cost savings to spend on other goods and services. So, if you have fewer people employed as a taxi driver because Uber has automatic cars, then those rides should be cheaper and people have more money to spend on something else.”
Jessop said banks are also using AI to improve productivity, with a single digital agent able to produce the output of 20 human employees.
Tasks banks are seeking to automate include account opening, transaction monitoring, fraud detection, document verification and customer service.
Higher productivity linked to AI across the economy should theoretically lower inflation, as businesses produce more without the need to raise prices, Jessop said.
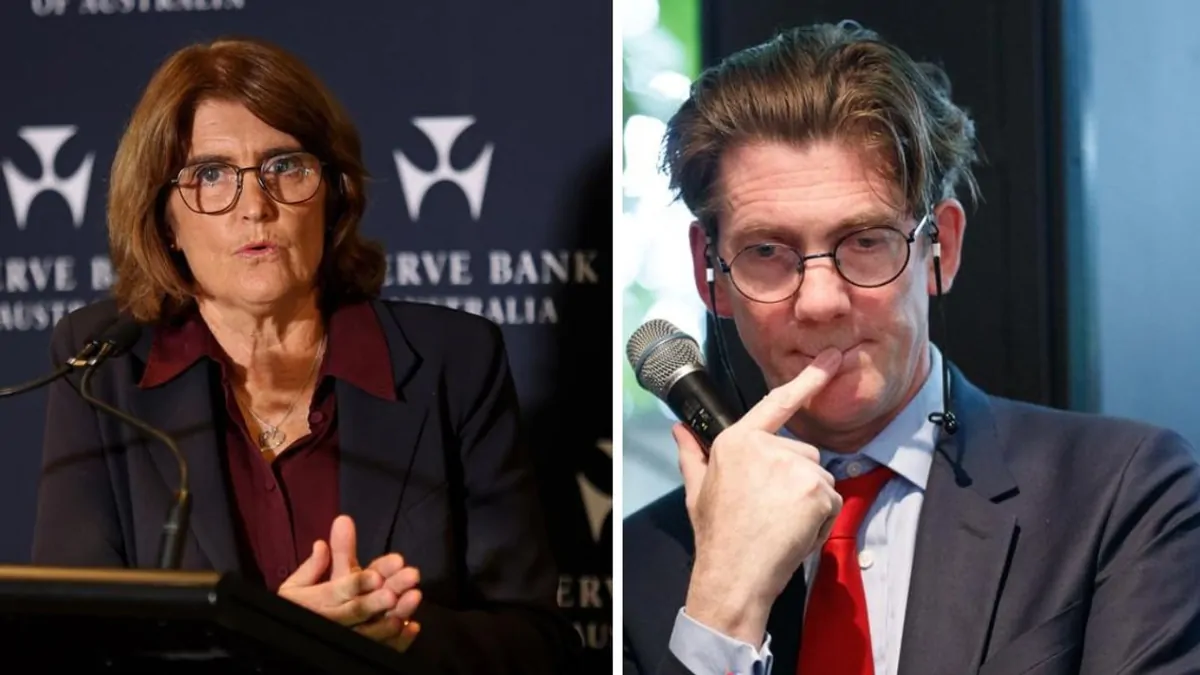
Demand for goods and services could also grow without running into supply limitations, with Reserve Bank Governor Michelle Bullock regularly blaming Australia’s feeble productivity for its inflation problem.
“All else being equal if productivity increases there is less pressure on inflation,” Jessop said.
“But you could take the benefits in different ways. One way to increase the benefits is everybody works shorter hours. So, a typical working week becomes four days rather than five, so that doesn’t affect inflation as the balance of supply and demand is the same, it’s just that people took four days to produce the same amount of supply whereas before they took five.”
Sector under pressure
The prospect of higher productivity is particularly important for banks, which have faced pressure to improve returns while meeting tough regulatory requirements.
Traditional lenders also face competition from digital financial companies including Square, Revolut, Wise and Airwallex, which operate without much of the branch infrastructure and compliance costs of the major banks.
“AI is a quantum leap forward,” Jessop said. “Previous tech revolutions, like the industrial revolution, replaced people doing manual labour.
Whereas AI is more about replacing the ability to think, so the risks are bigger, but the precedents of the past are encouraging. Some jobs are lost, but better ones are created elsewhere in the economy.”
Shares in London Stock Exchange listed Barclay’s dropped 1.4 per cent on Thursday, despite it saying the job cuts will help it save more than £1.1bn ($2 billion) in 2027.
Australia’s S&P/ASX 200 Financials sector dominated by the big-four banks is down 3.4 per cent over the past 12 months, versus a 2.6 per cent fall for the benchmark S&P/ASX 200 Index.
Australia’s four major banks employ about 170,000 people, including roughly 55,000 at CBA, 40,000 each at ANZ and NAB and 35,000 at Westpac.
Across the broader financial and insurance services industry, 559,600 people were employed in August, according to the Australian Bureau of Statistics, up 4.8 per cent from a year earlier.